Home Economics, Policy & Regulation Global Economy Struggles to Achieve Balance in Divided Times
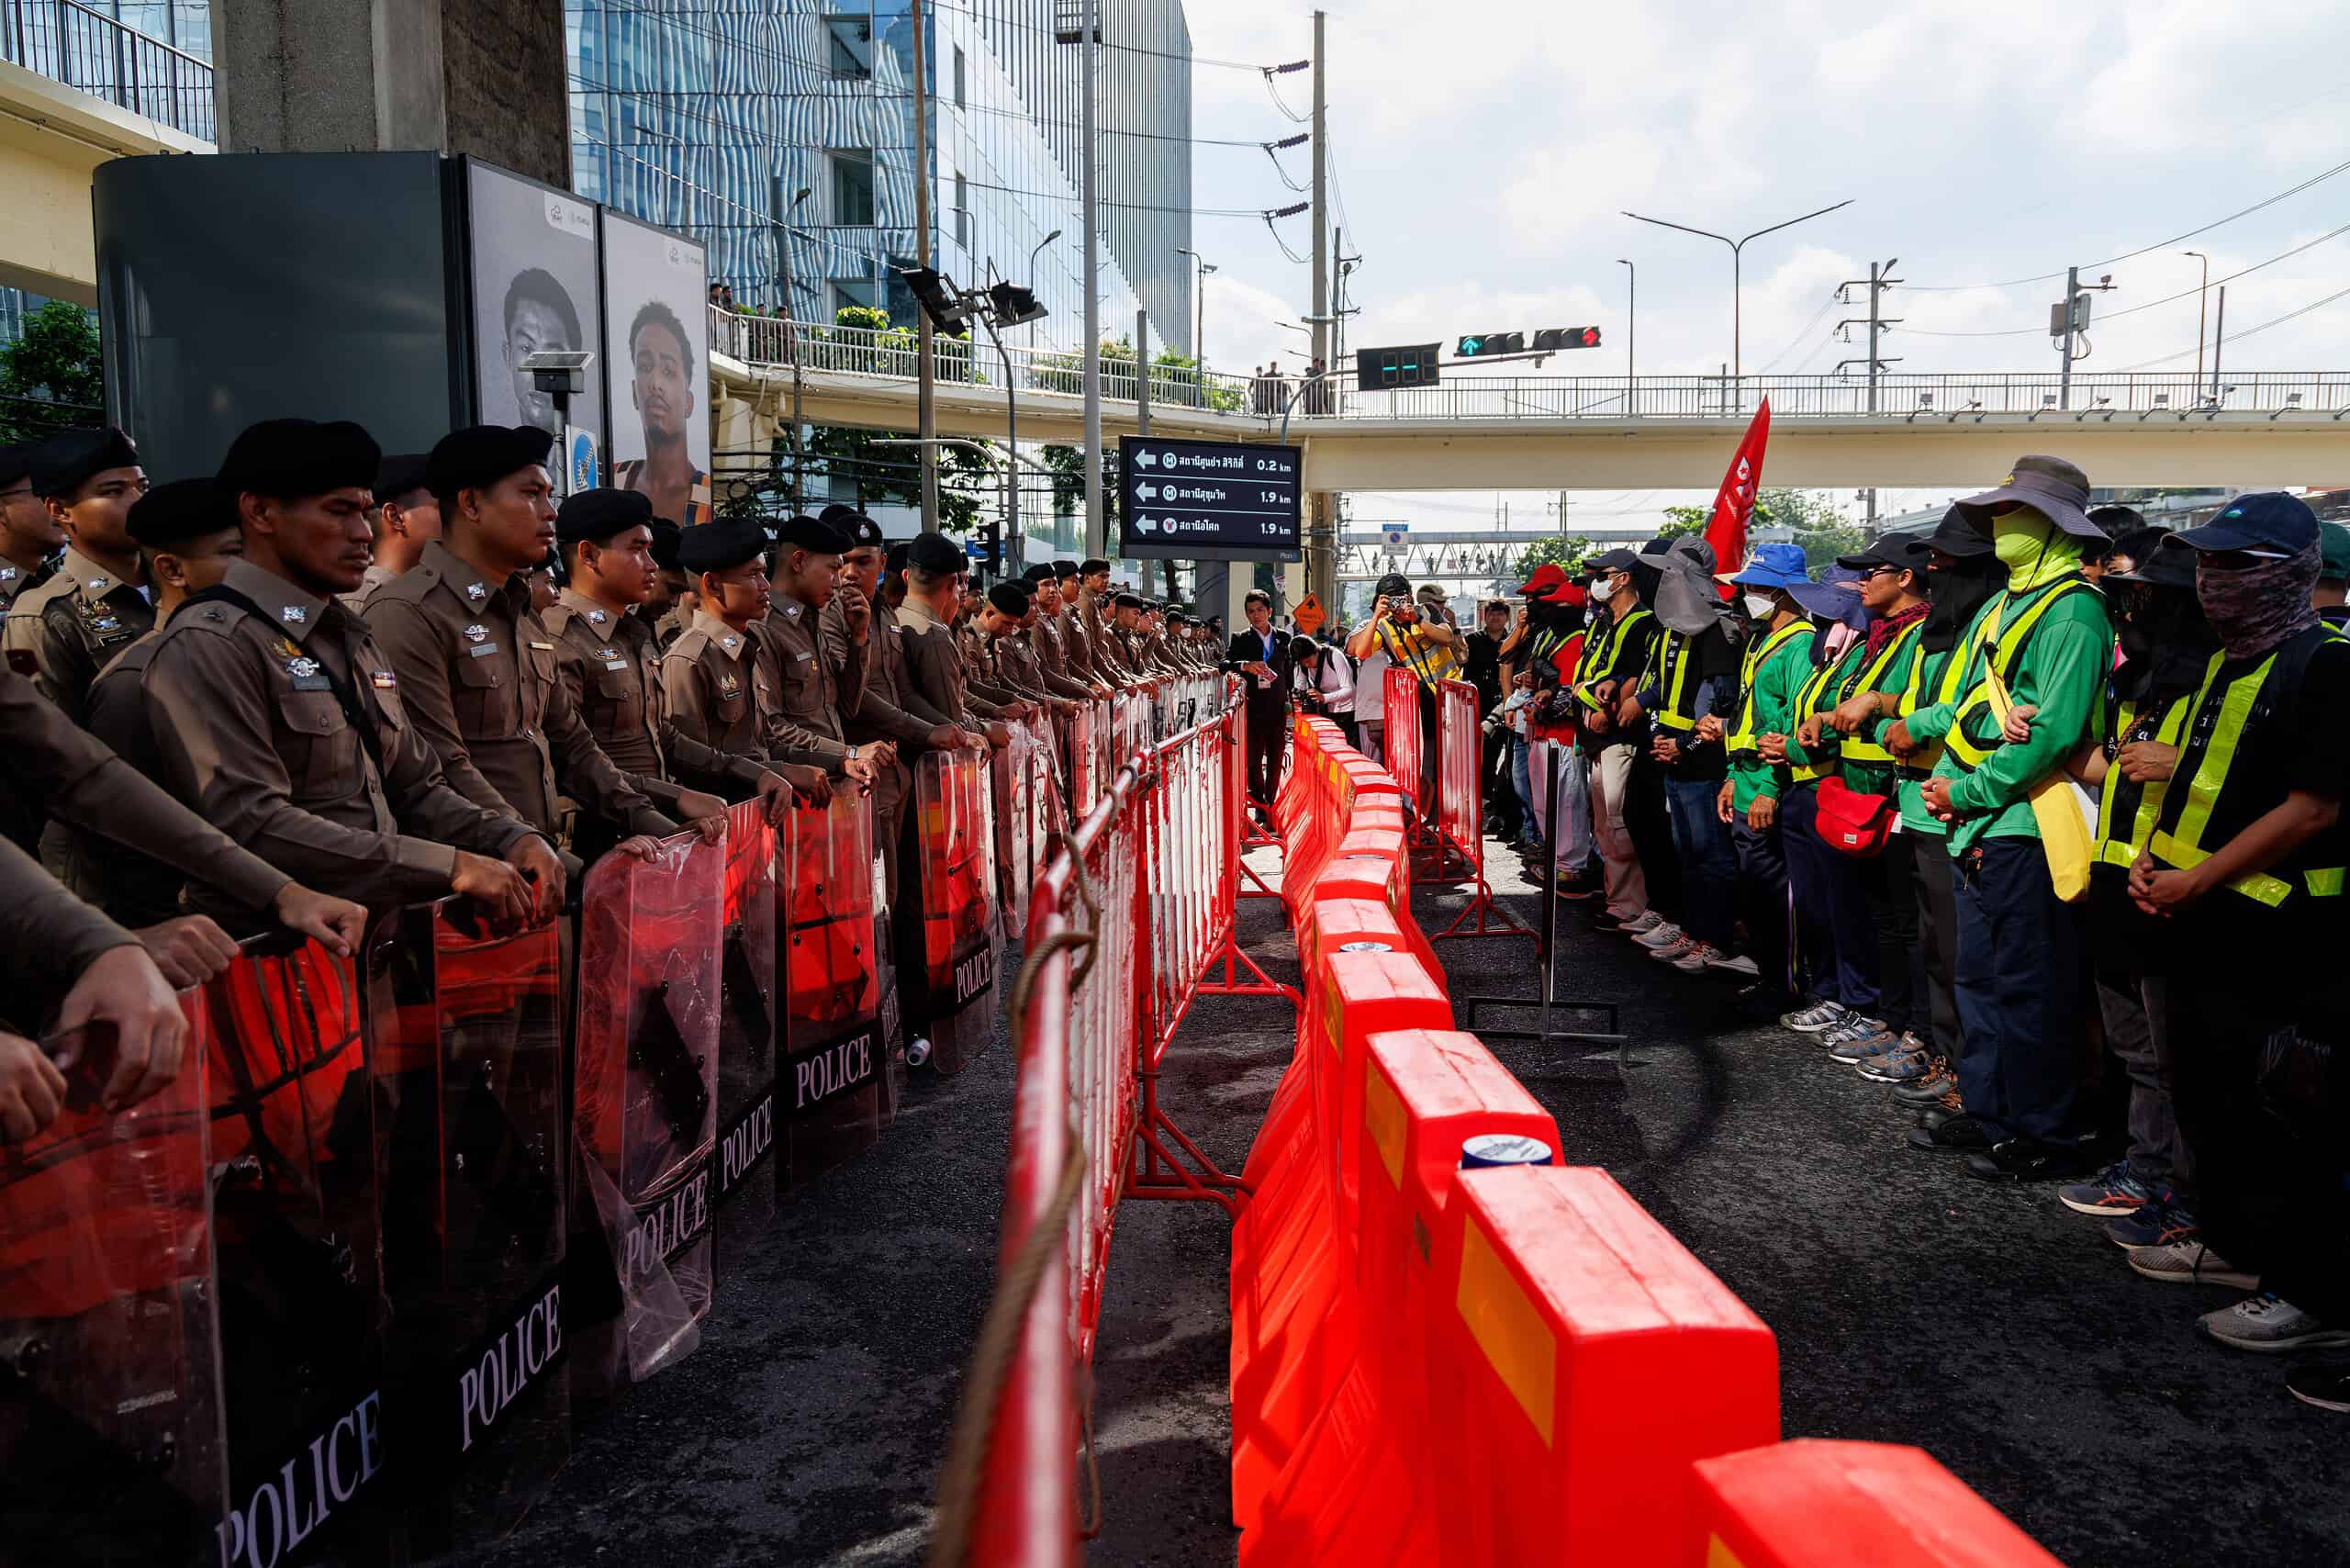
As leaders gathered in Bangkok, discussions highlighted the fractures between economic winners and losers.
The global economy appears to be on a fragile foundation, and the finance ministers of Argentina, Greece, Nigeria, and Thailand agree that all economies should get their houses in order.
“Ideally, when you put your fiscal house in order, it shouldn’t be because of experience,” said Kyriakos Pierrakakis, the Minister of Economy and Finance for Greece and President of the Eurogroup, during a panel discussion that took place at the annual International Monetary Fund (IMF) and World Bank meetings in Bangkok. “It should be because of inspiration.”
Although the IMF projects global economic growth at 3.1% throughout 2026, its composition has changed.
The global economy is increasingly split between a handful of nations with AI-driven economies and those without. The IMF has upgraded AI-driven economies while it downgraded many fuel-importing nations and those affected by war.
However, AI may be a curse and a blessing.
“The global economy’s dependence on AI investment enthusiasm creates a vulnerability, with risks of disappointment cycles, as per Amara’s Law , and the potential loss of human control over AI systems,” said fellow panelist Kristalina Georgieva, IMF Managing Director.
Exacerbating the situation are growing excessive export-import imbalances . Developing countries struggle to compete with export-oriented countries that have built their manufacturing base over decades. At the same time, developing economies struggle to compete for capital against an economy that takes in capital for productive use but leaves little for the rest of the world.
“The biggest source of imbalance comes from the two largest economies, China and the United States: China not having enough domestic consumption, exporting a lot, and the U.S. the opposite, not saving enough, having a high level of debt and deficit,” she said.
It’s best for a country to put its fiscal house in order during periods of economic calm, but human nature tends to act only amid a crisis, said Georgieva. “Nonetheless, we have excellent examples of countries that have brought back fiscal discipline. They have taken the reforms, structural reforms that promote growth.”
The formula for building a resilient economy is discipline, transparency, and consistency, which, according to Olayemi Cardoso, Governor of the Central Bank of Nigeria, build credibility, said Cardoso, who spoke on the panel.
To address a persistent currency crisis and the loss of investor confidence, Nigeria eliminated its fuel subsidy in 2023 and, in June 2024, implemented multiple foreign exchange rates.
“These should have been done a long time ago, but they were not done,” he said.
The central bank also enacted an aggressive 800-basis-point (bp) increase in 2024, including a single 400-bp increase. As a result, the central bank brought inflation down by about 20 percentage points, to about 15%, and raised foreign reserves to their highest level in 18 years.
“Painful though they were, it brought back credibility because we were consistent in saying certain things and doing them,” said Cardoso.
In Argentina, the government eliminated its fiscal deficit, which was 5% of GDP, by cutting spending by 30% and growing the economy for the third consecutive year through increased exports. These measures help…